campusinternal

5 Super Easy Ways To Save Money While Living On Campus


July 8, 2019 | Eul Basa

5 Super Easy Ways To Save Money While Living On Campus


Living frugally is challenging when you're a college student. Not only are you faced with mandatory purchases like tuition, rent, and textbooks, you also come across a couple of other miscellaneous expenses that can really cut deep into your wallet. The groceries for your section of the fridge, the cover fees for various campus events, and even the iced coffees you buy every morning that always causes you to be late for your lecture can all rack up the costs (and fast).

As stressful as it can be to deal with all of these, staying financially afloat can be as simple as a maintaining a good budget, employing your financial skills efficiently, and taking advantage of the resources that are available to you. It's a valuable lesson you'll learn while living on campus that isn't given in a lecture hall. Read on for 5 super easy ways to save money while living on campus:

Image result for college studentsJoin Knack

Don't forget to check the comment section below the article for more interesting stories!

#1 Use student discounts

Typically, local businesses near colleges will have student discounts. There may be some cafes that offer lower-priced drinks, or clothing stores that give a 15% discount.  If you're looking to save money while on campus, it would be a good idea to scout your area for these businesses and make a note of the discounts they offer to students.

Also, don't forget about your student ID—it may be able to get you certain products and services at cheaper prices. For example, many campuses offer things like free gym memberships and lower bus fare rates to students who can present a valid student ID. Just make sure to look up exactly what you can avail of with it so you're prepared.

Image result for college students shoppingGrad Shop

Advertisement

#2 Do research on your courses

Before the start of every term, plan out exactly what you'll need for each of your courses. Are there any required textbooks? Do you need an iClicker? Is there an accompanying lab you'll need to buy additional course materials for? Knowing exactly what you need will help you manage your finances so you aren't surprised with anything once the term starts.

Also, get into the habit of reading online forums and asking around—people who have taken the course before may be able to give valuable advice, especially when it comes to determining the bare essentials you'll need to pass. For example, some professors will list certain textbooks as mandatory, but you might not even need to buy them since their course notes are detailed enough.
Image result for college studentsConsumer Reports

Advertisement

#3 Opt-out if you can

Some universities have various non-essential, non-tuition packages that are often overlooked. These could include fees related to things like student health and dental plans or even faculty donations. While a lot of the fees go towards funding groups that enrich student life, they are nevertheless ancillary, and some campus organizations do give students the option to opt out of them.

In some cases, opting out of something like your student health and dental plan may be worth it, especially if you already have your own insurance. In some schools, the opt-out will put a few dollars back into your pocket. Just make sure to be aware of the opt-out deadlines so you don't miss out on the opportunity. For more advice on this, seek out a financial aid officer on campus.

Related imageAIER

Advertisement

#4 Divide and conquer

If you live with roommates, try to help each other out by splitting some living expenses. After all, you will be sharing the space together, so it would only be fair to evenly distribute the responsibilities. For example, maybe you can take turns covering the toilet paper refills for the washroom, or paying for the take-out during your weekend hangouts. Sharing is caring!
Image result for college roommatesStudy Breaks

Advertisement

#5 Limit the eating out

Eating out is expensive, especially if you do it every day. It's probably the biggest expense that college students have when it comes to campus living. Just think about it—if one meal averages around $12 each, and you buy three meals a day, you'd spend $36 on food; just for that one day. That's $36 that could have gone to something else.

If you don't have a student meal plan, perhaps it would be a good idea to buy your own groceries. Cooking your own food will be cheaper than going out to eat or buying takeout because at least you'll have a bit more control over the prices. Save the restaurant dining for more special occasions, like if you pass an exam or nail your term paper.
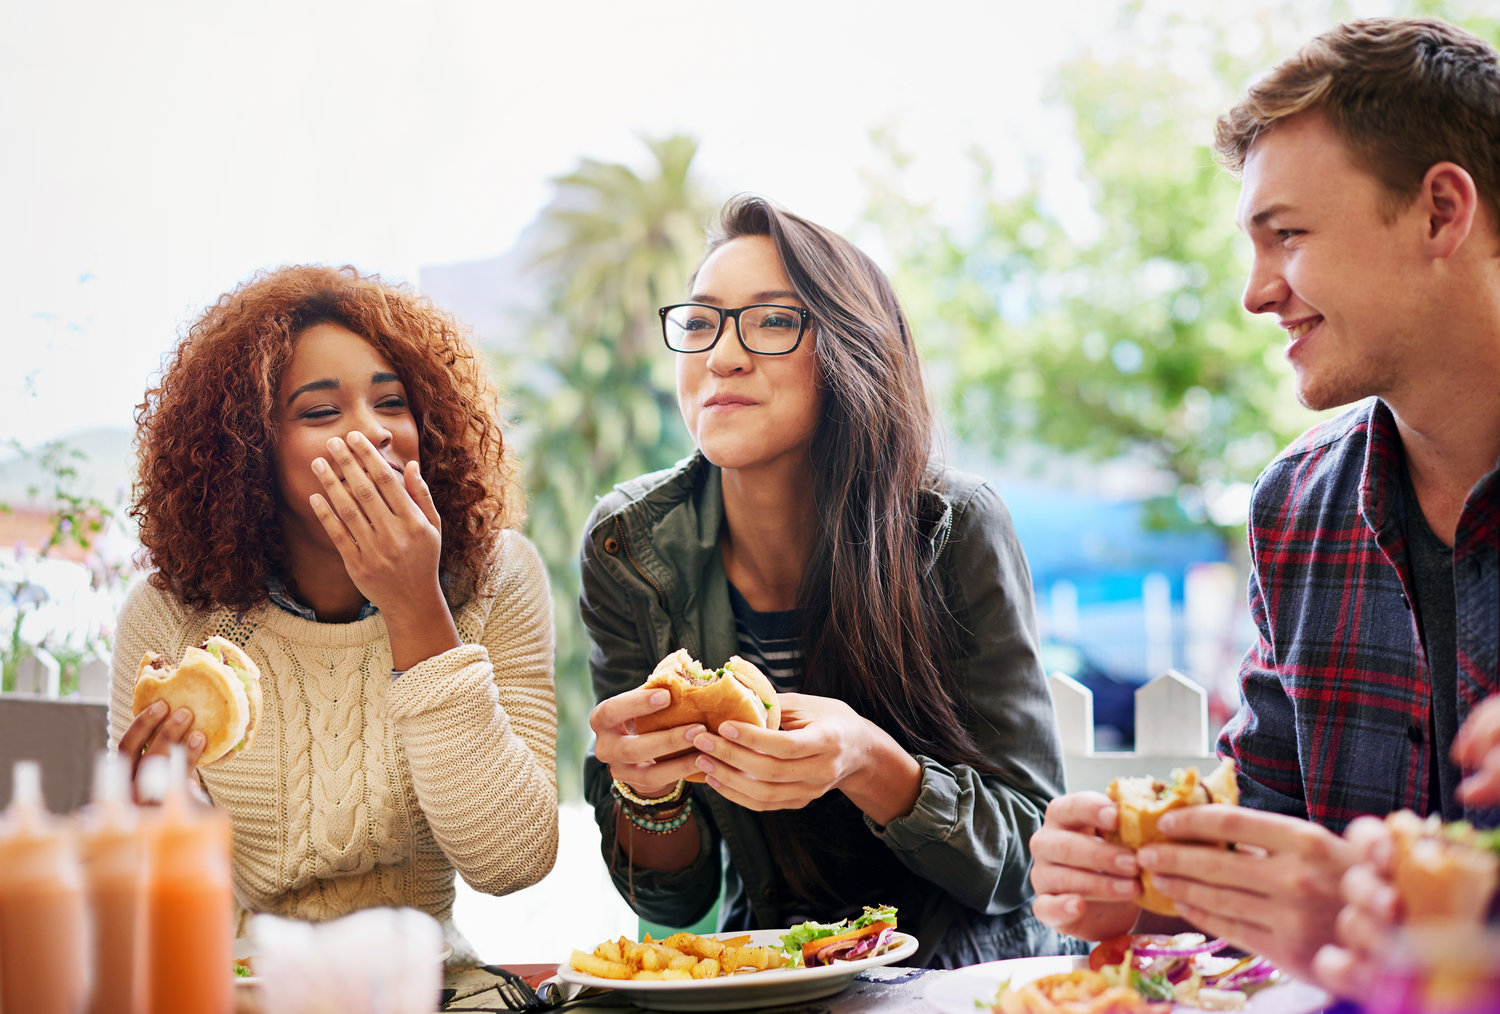
Image result for college students eating fast foodChartwell Student Success

Advertisement


READ MORE

Borders Books at 1807 Fordham Boulevard in Chapel Hill, North Carolina.

How Borders Books Lost Its Retail Advantage Before Its Final Bankruptcy

Borders once seemed unbeatable, with enormous selections and inviting stores built for browsing. Its collapse was not simply the result of e-books. Years of strategic decisions left the bookseller exposed when shopping habits changed.
November 11, 2026 J. Clarke
A man and woman collaborating on a project using a laptop at an office desk.

My friend says a 0% financing deal is always better than paying cash. Are there hidden costs he isn't considering?

A friend who swears by 0% financing is not completely wrong. Promotional financing can be a smart move when you qualify, keep the cash invested or available for emergencies, and pay every dollar before the promo ends. But the fine print can turn a great-looking deal into an expensive one fast, which is why the Federal Trade Commission and Consumer Financial Protection Bureau have both warned shoppers to read the terms carefully.
November 12, 2026 Miles Brucker
Family Portrait with a Toy Truck

My father wants me to cosign his new truck because he's retired and has little income. I want to, but it derail my own mortgage?

When a retired parent asks you to cosign a truck loan, it can feel less like a financial decision and more like a loyalty test. But cosigning is not a symbolic gesture. According to the Consumer Financial Protection Bureau, a cosigner becomes legally responsible for repaying the full loan if the primary borrower does not pay.
November 12, 2026 Miles Brucker
Facebook   Internal

My wife wants to give our children their inheritance now to see them enjoy it. What could go wrong with early gifts?

It is easy to see the appeal of handing children part of their inheritance while you are still around to watch them use it. A down payment, student loans, or help with childcare can change a family’s trajectory much more at 35 than at 65. But once money leaves your control, a heartfelt gift can create tax headaches, family resentment, or even leave you short later in life.
November 12, 2026 Miles Brucker
Facebook   Internal

My employer says I have to repay training costs if I quit within three years. Can a job legally come with an exit fee?

You accept a new job, sign the onboarding packet, and then spot a clause that says you owe thousands of dollars if you leave too soon. It sounds like an exit fee, and for many workers it feels like a trap. The good news is that these clauses are not automatically enforceable just because an employer put them in writing.
November 12, 2026 Miles Brucker
The Deal Sounds Simple Until It Doesn't

My brother offered to buy my share of our family business, but wants to pay me from future profits. Is that a really risky deal?

In the short term, your brother buying your share of the family business, to be paid from future profits, keeps things fair, flexible, and low-drama, but it can also leave you holding far more risk than you think. The real question is not whether your brother means well. It's whether your financial plan still works if profits drop, get delayed, or never arrive.
November 12, 2026 Miles Brucker


Disclaimer

The information on MoneyMade.com is intended to support financial literacy and should not be considered tax or legal advice. It is not meant to serve as a forecast, research report, or investment recommendation, nor should it be taken as an offer or solicitation to buy or sell any securities or adopt any particular investment strategy. All financial, tax, and legal decisions should be made with the help of a qualified professional. We do not guarantee the accuracy, timeliness, or outcomes associated with the use of this content.


Dear reader,


It’s true what they say: money makes the world go round. In order to succeed in this life, you need to have a good grasp of key financial concepts. That’s where Moneymade comes in. Our mission is to provide you with the best financial advice and information to help you navigate this ever-changing world. Sometimes, generating wealth just requires common sense. Don’t max out your credit card if you can’t afford the interest payments. Don’t overspend on Christmas shopping. When ordering gifts on Amazon, make sure you factor in taxes and shipping costs. If you need a new car, consider a model that’s easy to repair instead of an expensive BMW or Mercedes. Sometimes you dream vacation to Hawaii or the Bahamas just isn’t in the budget, but there may be more affordable all-inclusive hotels if you know where to look.


Looking for a new home? Make sure you get a mortgage rate that works for you. That means understanding the difference between fixed and variable interest rates. Whether you’re looking to learn how to make money, save money, or invest your money, our well-researched and insightful content will set you on the path to financial success. Passionate about mortgage rates, real estate, investing, saving, or anything money-related? Looking to learn how to generate wealth? Improve your life today with Moneymade. If you have any feedback for the MoneyMade team, please reach out to [email protected]. Thanks for your help!


Warmest regards,

The Moneymade team


✕